TSMC, the world’s largest manufacturer of advanced semiconductors, struck a cautious note regarding its outlook for 2027 on Thursday, citing macroeconomic uncertainties that temper an otherwise exceptionally strong performance. The company reported a sixth consecutive quarter of record profit, driven by robust demand tied to artificial intelligence, but signalled that it would not allow optimism to override careful planning. While Taiwan Semiconductor Manufacturing Co described demand as extremely robust and said it sees no indication of a slowdown in what it characterises as the artificial intelligence mega trend, the company made clear that caution would guide its approach to the year ahead.
Chief Executive C.C. Wei addressed the matter directly during an earnings call. “Looking ahead, we continue to observe consumer and price-sensitive end-markets segments are being challenged due to the impact of rising component prices and macroeconomic uncertainties,” he said. “As such, we are being prudent in our business planning going into 2027.” Those remarks captured the delicate balance the company is attempting to strike between capitalising on extraordinary demand and preparing for potential headwinds that could emerge as economic conditions evolve. Net profit for the third quarter jumped sixty nine percent to 763.1 billion Taiwan dollars, surpassing analyst forecasts and underscoring just how central TSMC has become to the global technology supply chain.
Despite the measured tone regarding 2027, TSMC reiterated that demand far exceeds its supply capacity, a dynamic that has persisted throughout the artificial intelligence boom. The company now expects full year revenue for 2026 to grow by approximately forty four percent, an upward revision from its previous forecast of greater than forty percent issued last quarter. It also maintained its capital spending expectation for 2026 at between sixty billion and sixty four billion dollars, signalling continued confidence in the long term trajectory of the market even as it exercises restraint in forward planning. The company pointed to the emergence of agentic artificial intelligence central processing units and continued demand for networking chips as forces that would drive future silicon demand, offering a glimpse into where it sees the next wave of growth originating.
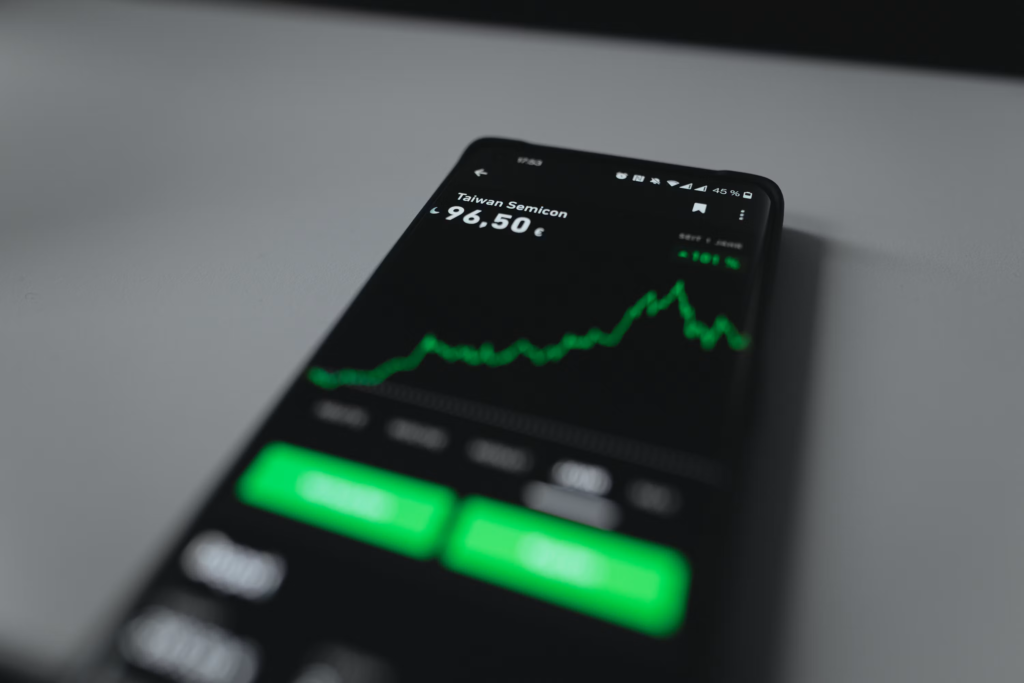
TSMC’s results arrived amid broader concerns that the artificial intelligence investment surge may be losing momentum, concerns that have rippled through equity and credit markets in recent weeks. On Wednesday, ASML, the world’s largest maker of tools used to manufacture artificial intelligence chips and advanced semiconductors, provided an upbeat outlook that offered some reassurance to investors worried about the sustainability of current spending levels. TSMC, a key supplier to Nvidia and Apple, said it expects fourth quarter revenue to rise by as much as sixty one percent from a year earlier, reaching between 52.3 billion and 54.3 billion dollars. That guidance reflects the continued strength of orders from major customers whose products depend on TSMC’s most advanced manufacturing processes.
Market reaction to the earnings release was muted, with TSMC’s Taipei listed shares closing down two percent ahead of the announcement, in line with a broader technology sell off driven by worries that additional interest rate hikes from the United States Federal Reserve could pressure shares of artificial intelligence companies that are particularly sensitive to higher borrowing costs. Shares of South Korean rivals Samsung Electronics and SK Hynix slid more than ten percent, illustrating how interconnected and how vulnerable to sentiment shifts the semiconductor sector has become. The divergence between TSMC’s operational performance and the market’s cautious posture highlights a tension that has defined the artificial intelligence trade for some time. The company is producing record profits and cannot manufacture chips fast enough to meet demand, yet investors remain alert to the possibility that the cycle could turn. Whether TSMC’s prudence proves prescient or overly defensive will depend on macroeconomic conditions that remain difficult